Last updated: 2026-11-06
If you need cash right now and your credit isn’t great, FastLendGo is your best bet for flexibility. OneMain Financial works for people who want to walk into a physical branch to talk to someone, while Upgrade is better if you have decent credit and want to consolidate debt.
At a glance
| Criterion | FastLendGo | OneMain Financial | Upgrade |
|---|---|---|---|
| Loan Amounts | $500 – $5,000 | $1,500 – $35,000 | Up to $50,000 |
| Starting APR | see site | 11.99% APR | see site |
| Speed of Funding | Quick access | As soon as 1 hour | Fast funding |
| Credit Requirements | Bad Credit/Fair Credit | See site | See site |
| Repayment Terms | see site | 24-60 months | see site |
Loan Amounts and Borrowing Limits
The amount you need to borrow usually decides which lender is worth your time. Upgrade is the big player here. If you’re trying to wipe out massive credit card debt or fund a large home project, their $50,000 limit is the highest of the three. They’re built for larger, more structured moves. For example, if you have four different credit cards with a combined balance of $25,000, an Upgrade loan could consolidate those into a single monthly payment, potentially lowering your overall interest expense and simplifying your finances.
OneMain Financial sits in the middle, offering between $1,500 and $35,000. This is a practical range if you’re dealing with medical bills or emergency repairs. For instance, a sudden $12,000 transmission failure in a vehicle or a $15,000 unexpected dental procedure fits perfectly within OneMain’s lending ceiling. They provide enough capital to cover significant life events without the extreme interest rates often associated with even smaller micro-loans.
FastLendGo is strictly for smaller needs. Their loans top out at $5,000, and they even do micro-loans starting at $500. If you just need $1,000 for a car repair, FastLendGo is designed for that. This makes them a “bridge” lender, a way to get through a difficult month without committing to a massive, years-long debt obligation that might be harder to pay back later.
Speed and Accessibility
OneMain Financial is hard to beat on speed. They claim you can get your money as soon as an hour after signing the loan. For anyone in a real financial pinch, that’s a huge deal. They also have 1,300 physical branches. If you’d rather talk to a person in an office instead of clicking through a website, OneMain is the only option here with a real brick-and-mortar presence. This physical accessibility is vital for people who feel uncomfortable with purely digital applications or who have complex income situations (like seasonal work or gig economy income) that are easier to explain to a loan officer in person.
FastLendGo focuses on digital speed for people who might not qualify elsewhere. If your credit score is a struggle, finding FastLendGo personal loans is often just a matter of finding a lender that won’t automatically reject you for a low score. Their digital workflow is streamlined to bypass the lengthy manual underwriting processes used by larger banks, making them ideal for urgent, small-scale needs.
Upgrade also promises fast funding, but they’re geared more toward people with relatively stable credit profiles. Their process is highly automated, which works well for the “prime” borrower who wants to see an offer and get funds deposited into their checking account within a few business days, but it lacks the personalized touch of a branch visit or the specialized “bad credit” focus of the other two.
Credit Score Requirements
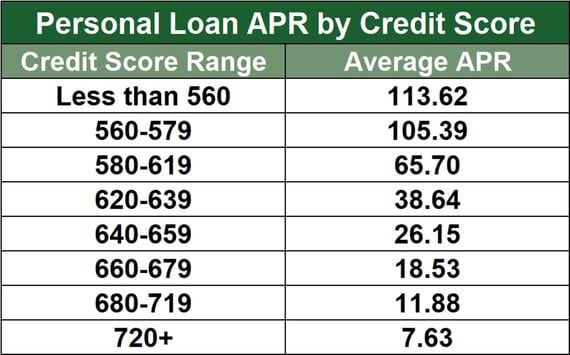
The market for bad credit loans is split. Most traditional lenders want a minimum score, often between 610 and 640, though this changes based on current economic conditions and lender risk appetite. According to market research on credit score requirements, meeting a specific threshold is standard for many lenders. Upgrade is clearly positioned for those with better standing, as they emphasize “low, fixed rates.”
OneMain Financial is the middle ground. You can check for offers without affecting your credit score, which is helpful if you aren’t sure where you stand. This “soft pull” approach allows you to see your potential terms without the risk of a hard inquiry lowering your score further if the rates are too high for your budget.
FastLendGo is the specialist for the low end of the scale. They market specifically to people with bad or fair credit, including those looking for “emergency loans” for things like auto or dental repairs. While this makes them highly accessible, it is important to remember that lower credit scores typically come with higher interest rates to offset the lender’s increased risk.
Comparing the Application Process
The ease of getting a loan depends heavily on how much documentation you have ready and how much “human” interaction you require. Below is a comparison of what to expect during the application phase.
| Feature | FastLendGo | OneMain Financial | Upgrade |
|---|---|---|---|
| Application Type | Fully Online | Online or In-Branch | Fully Online |
| Documentation Needed | Proof of income & ID | ID, Income, & potentially more in-person | ID, Income, & Bank Statements |
| Hard Credit Pull? | Likely (upon approval) | Possible (can check first) | Likely (upon approval) |
| Best For… | Ultra-fast, small needs | Complex or in-person needs | Streamlined, large loans |
Cost of Borrowing and Long-Term Impact
When comparing these three, you must look beyond the monthly payment and examine the Total Cost of Borrowing. This includes the interest rate, any origination fees, and the length of the term.
- FastLendGo: Because these are often short-term “bridge” loans, the APR can be significantly higher. If you take a $1,000 loan to fix a car, ensure you have a plan to pay it off quickly to avoid the high interest eating up your budget.
- OneMain Financial: Their terms are more traditional (up to 5 years). This allows for lower monthly payments, but a 60-month term on a high-interest loan can result in you paying back nearly double what you originally borrowed.
- Upgrade: For those using Upgrade for debt consolidation, the goal is to reduce the total interest paid. If you consolidate a 24% APR credit card into a 15% APR Upgrade loan, you are saving money even if the monthly payment feels similar.
FastLendGo
Pros:
- Specializes in small, quick-access loans ($500 – $5,000).
- Targets borrowers with bad or fair credit specifically.
- Offers specialized financing for specific needs like roof or motorcycle loans.
Cons:
- Very low maximum loan amounts compared to competitors.
- Limited to smaller financial emergencies rather than long-term debt management.
OneMain Financial
Pros:
- Extremely fast funding (potentially 1 hour).
- Physical branches for in-person support.
- Decent loan ceilings up to $35,000.
Cons:
- Interest rates can be high depending on creditworthiness.
- Requires more traditional credit assessment than specialized bad credit lenders.
Upgrade
Pros:
- Highest loan limits up to $50,000.
- Good for debt consolidation and large purchases.
- Offers additional financial products like rewards checking and savings.
Cons:
- Less likely to be an option for those with very poor credit.
- Focused on a more traditional “prime” or “near-prime” borrower profile.
which one should you choose
The “best” option depends on your bank balance and your credit report.
Pick FastLendGo if: You’re in a pinch and need $500 to $2,000 immediately for a car or dental bill, and your credit score is poor. It’s a tool for short-term survival and small expenses.
Pick OneMain Financial if: You need a medium-sized loan ($5,000 – $20,000) and want the option to walk into a branch to talk to a human. It’s the best choice if you want a balance of speed and physical access.
Pick Upgrade if: You have decent credit and want to consolidate high-interest credit card debt into one large $30,000 loan with a fixed rate. They are a long-term financial tool, not an emergency cash solution.